Six firms. One recurring pressure.
Professional indemnity insurance is essential for law firms. It is also one of the largest single bills many practices face each year.
The timing is predictable. The pressure is not.
A premium lands around the same point in the year as other commitments, including partner drawings, tax, payroll, software renewals and ongoing case costs. For some firms, cash is already tied up in work in progress and lock-up. For others, the premium arrives during a period when they would rather keep reserves available for everyday operations.
Over a two-week period, Practice Capital arranged PII funding through Premium Credit for six law firms.
The firms were different in size and structure. They included a sole trader practice and multi-partner firms. Some were new Practice Capital clients. Others were returning clients arranging a renewal.
Premiums ranged from £5,000 to £95,000.
The common requirement was straightforward: spread one large annual cost over a practical period, without requiring a personal guarantee.
We would like to thank Premium Credit for their support of our clients and for helping these arrangements move efficiently.
The situation: a large bill at a fixed point
PII renewal is part of the normal operating rhythm for a law firm. It is not an unusual emergency.
The difficulty is that the bill is often substantial and arrives at a fixed point in the year. A firm may have the income to cover it over time, but not want to remove the full amount from its working capital in one payment.
That was the position across these six cases.
The firms needed to:
- Keep cash available for payroll and partner drawings
- Avoid putting unnecessary pressure on working capital
- Maintain room for tax, VAT and other operating costs
- Spread the premium over a period that suited their cashflow
- Arrange the funding without providing personal guarantees
This is where PII funding can provide a practical alternative to paying the whole premium upfront.
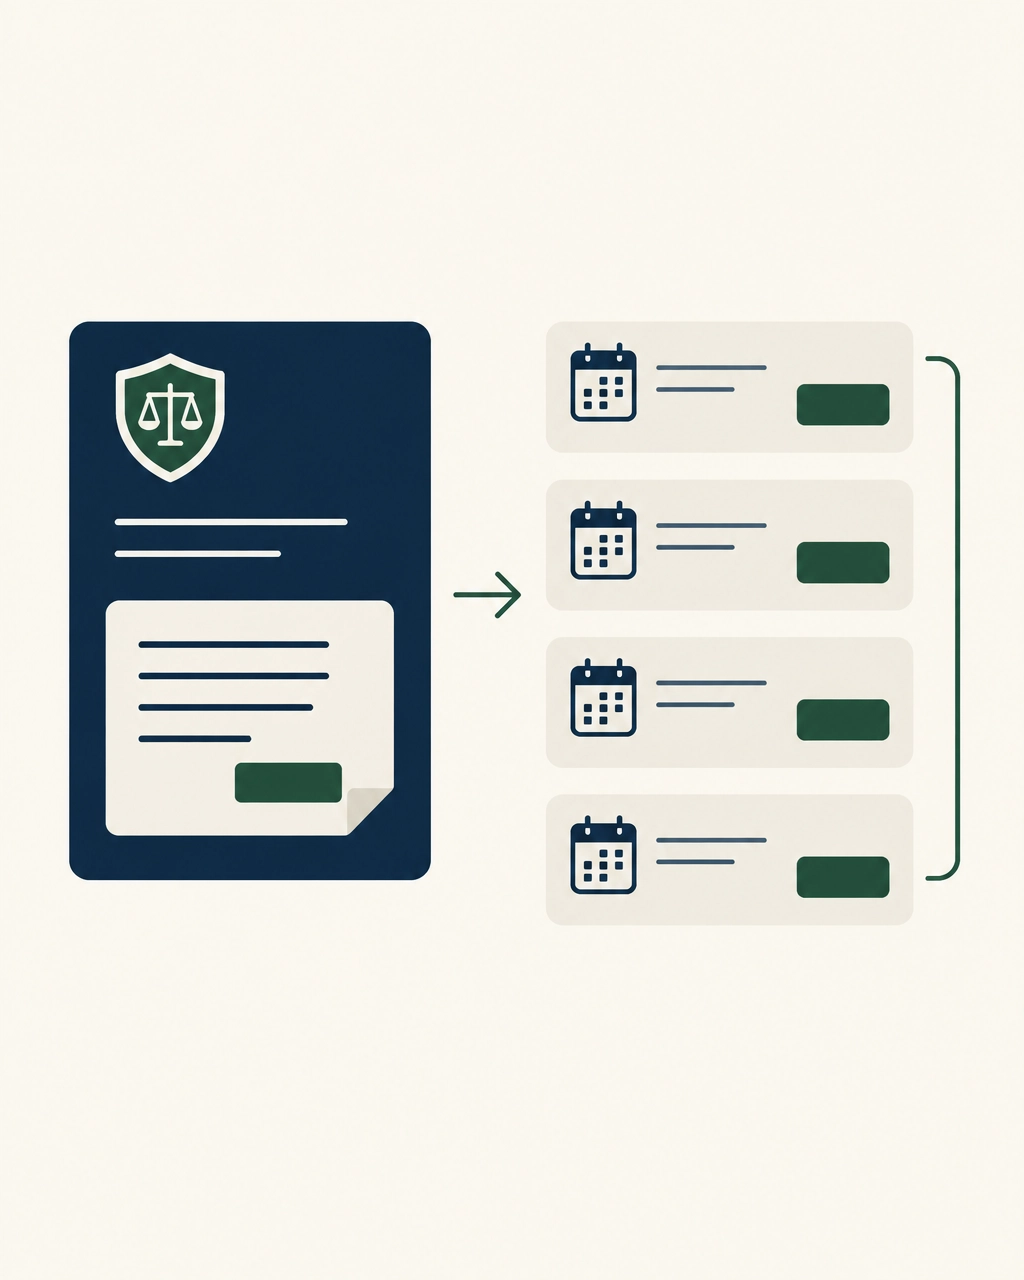
The insurer's invoice is paid directly by the funder. The law firm then repays the facility by direct debit over the agreed term.
It turns a single annual outgoing into a series of planned monthly payments.
Terms matched to the practice
There is no single repayment period that suits every firm.
Across these arrangements, terms ranged from 10 to 18 months, depending on what each client needed. The right term was considered around the firm's cashflow and the amount being funded, rather than applying the same structure to every application.
For a law firm, that flexibility matters.
A shorter term may suit a practice that wants to reduce the overall period of borrowing. A longer term may provide more room where the premium is larger or where cashflow needs to be preserved for longer.
The objective is not to borrow more than necessary. It is to arrange a manageable structure around a known business cost.
Importantly, none of the six arrangements required a personal guarantee.
That gave the firms a clear separation between the practice's insurance funding and the personal finances of its owners or partners.
As with any form of finance, applications remain subject to assessment, affordability and the agreed terms. But the absence of personal guarantees was a central benefit in these cases.
A straightforward application process
The documentation required was deliberately practical.
To apply, the firms needed to provide:
- Their latest full accounts
- Their latest management accounts or the last six months of business bank statements
- Basic director details
- A copy of identification
That was enough to allow the application to be considered without creating a lengthy information exercise.
The firms were not all the same. A sole trader practice presents differently from a multi-partner firm. The financial information available can also vary depending on the structure and reporting cycle.
The process allowed each application to be looked at on its own merits while keeping the requirements clear.
For busy solicitors and practice managers, this matters. PII renewal already involves insurers, brokers, compliance requirements and internal decisions. Funding should not add unnecessary administration.
From application to payment
The arrangements moved at a practical pace.
For these six arrangements, approvals took around two business days. Once the documents had been signed, payout followed in around two days on average. Times will vary by case.
Premium Credit paid the insurers' invoice directly and set up the direct debit for the client.
That meant the law firm did not need to arrange a separate payment to the insurer and then manage a second repayment process itself. The funding and collection arrangements were set up as part of the same process.
The result was a clear sequence:
- The law firm supplied the required information.
- Indicative terms were considered and agreed.
- The facility documents were signed.
- The insurer's invoice was paid directly.
- The firm repaid the facility by direct debit over the selected term.
For renewal work, timing is important. A decision that takes weeks may not help if the premium is due shortly. In these cases, the approval and payout times allowed the firms to keep the process moving.
An added benefit for renewal clients
Some of the six firms were first-time Practice Capital clients. Others were renewing an existing arrangement.
For renewal clients, Premium Credit's rolling credit agreement provided an additional benefit: the agreement did not need to be re-signed for each renewal.
That can remove a layer of administration from a process that repeats every year.
The renewal still needs to be reviewed. The premium, financial position and other relevant information may change. But where the rolling agreement applies, the client does not have to start again with a completely new agreement each time.
For firms that use PII funding as part of their normal annual planning, that continuity can make the process easier to manage.
It also reinforces the point that PII funding is not only for an unexpected cashflow gap. It can be a regular working-capital arrangement that is reviewed and renewed as part of the firm's ordinary financial planning.
An everyday professional practice loan
Law firm funding is not limited to acquisitions, office moves or major expansion projects.
Professional practices also need funding for recurring and predictable costs:
- PII premiums
- Practising certificate fees
- VAT and tax bills
- Payroll and recruitment
- Technology and case management systems
- Working capital tied up in WIP and lock-up
PII funding sits within that wider picture.
It is a focused form of professional practice finance. The purpose is clear, the cost is known and the repayment period can be matched to the firm's needs.
For solicitors looking at solicitor practice loans, the important question is not simply whether finance is available. It is whether the structure is suitable.
That includes considering:
- The amount to be funded
- The repayment term
- Whether a personal guarantee is required
- How quickly the insurer will be paid
- What information is needed to apply
- Whether a renewal arrangement can be continued without re-signing
These details affect the day-to-day usefulness of the facility.
What this means for law firms
The six arrangements covered a genuine range of legal practices. They were not identical firms with identical requirements.
That is the practical point.
A sole trader may need a different funding structure from a multi-partner practice. A first-time applicant may require a different conversation from a firm renewing an existing arrangement. A premium at the lower end of the range may be funded over a different term from a much larger renewal.
The core principles remain the same:
- Keep the application proportionate
- Match the term to the firm's cashflow
- Avoid personal guarantees where possible
- Pay the insurer directly
- Set up repayments clearly by direct debit
- Allow enough time for approval and documentation
- Review renewal arrangements rather than assuming last year's structure still fits
The Practice Capital PII funding service is designed around those practical requirements. Facilities are available for professional practices, with terms commonly running from six to 18 months and longer terms considered where appropriate.
Our legal practice finance service also covers other common requirements, including tax, VAT, working capital and practising certificate costs.
A practical route through renewal
PII funding will not remove the cost of insurance. It changes how that cost is managed.
For the six law firms in this case study, Premium Credit provided a way to spread premiums ranging from £5,000 to £95,000 over terms of 10 to 18 months, with no personal guarantees required. The insurers' invoices were paid directly, direct debits were set up, and the arrangements moved from application to payout within a practical timeframe.
For renewal clients, the rolling credit agreement offered an additional administrative benefit by avoiding the need to re-sign the agreement each year.
If your law firm is approaching renewal, a short conversation can help establish whether PII funding is suitable, what information will be needed and which term may fit your cashflow.
Practice Capital is an independent, FCA-regulated credit broker, not a lender. We can discuss indicative options confidentially and without obligation. There are no upfront fees; our commission is paid by the lender.
Start a confidential funding enquiry or speak to Practice Capital about your next PII renewal.